Data Centres vs SMEs: Buying a Factory in Selangor's Industrial Corridors in 2026
Hyperscale buyers are paying for big Selangor land parcels. Here is what that means, and what it doesn't, for an SME buying its own factory.
Originally published on Medium: read it on Medium
If you run a manufacturing, logistics or trading business in the Klang Valley, you have seen the headlines: data centre operators are buying large Selangor industrial parcels for hundreds of millions of ringgit.
Does this push factories out of reach, or is it a different market? Partly both. Here is what the published data shows, how the corridors differ, and what to check before you buy.
Important: this is general information drawn from public sources as at October 2026. It is not financial, legal, tax or engineering advice. Please get your own lawyer, banker and, where relevant, engineer to review any purchase.
The market in numbers
Start with the national picture, then the Klang Valley.
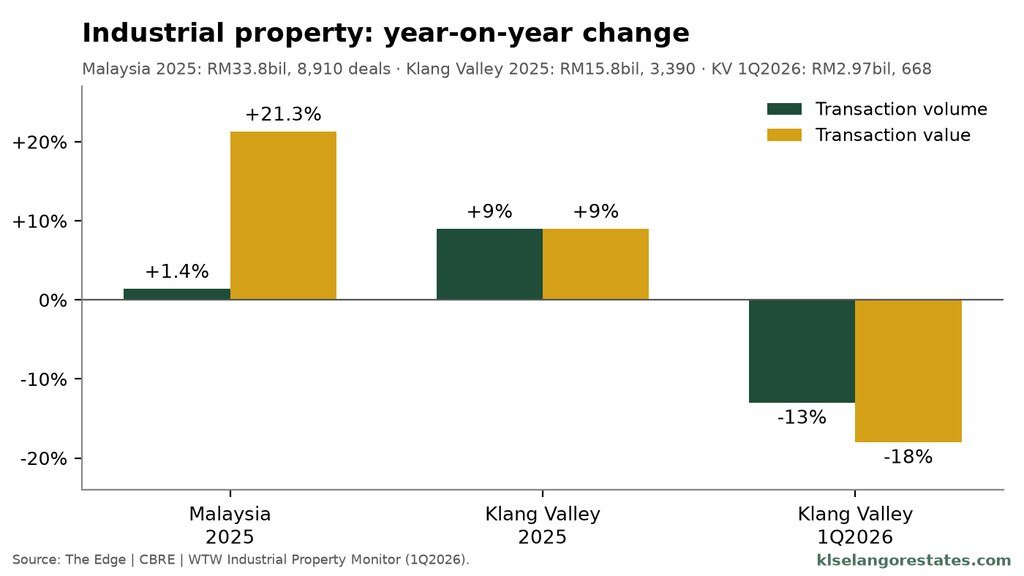
- 2025, Malaysia: industrial transaction value rose 21.3% year on year to RM33.8 billion, while volume rose only 1.4% to 8,910 transactions. CBRE | WTW reads this as buyers favouring larger, higher-value assets (The Edge | CBRE | WTW Industrial Property Monitor, 1Q2026).
- 2025, Klang Valley: 3,390 transactions worth RM15.8 billion, both up 9%.
- 1Q2026, Klang Valley: activity cooled. Volume fell 13% to 668 transactions and value fell 18% to RM2.97 billion, which CBRE | WTW attributes mainly to subdued investment sentiment.
- 1H2026, Malaysia: NAPIC recorded 3,932 industrial transactions worth RM14.78 billion (reported by The Edge at the launch of the 1H2026 Property Market Report).
For warehouses, CBRE | WTW's 1Q2026 snapshot reports about 2.8 million sq ft completed in the quarter, occupancy dipping to 96.1%, and about 7.2 million sq ft of new supply expected by end-2026, which may pressure occupancy and rents.
So the market is not simply "hot": big deals lift headline values while day-to-day activity has slowed.
How data centre demand actually reaches you
The big land deals
Two Selangor transactions show the scale.
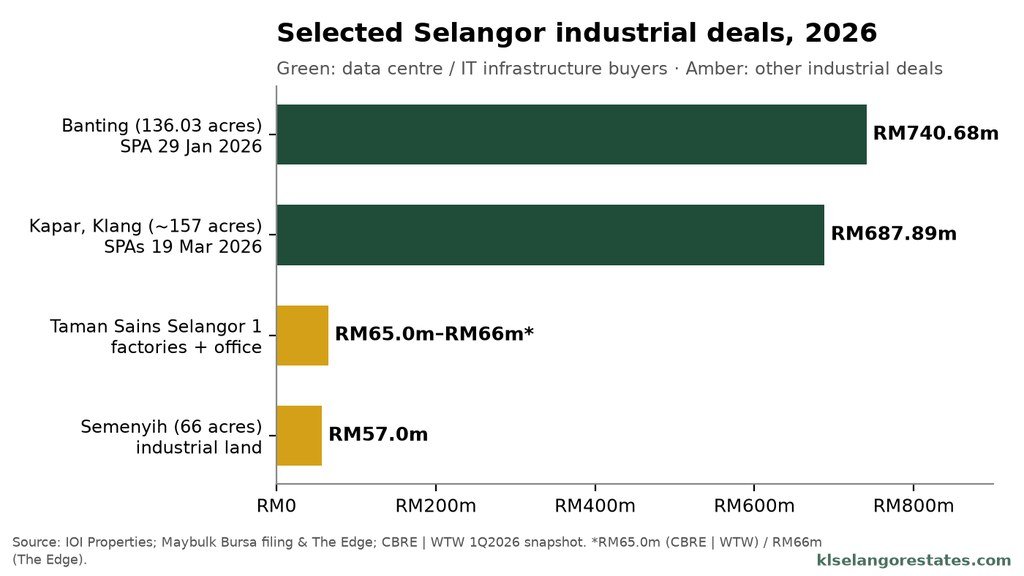
- Banting: IOI Properties' subsidiary Fortune Growers signed an SPA on 29 January 2026 to sell three plots in IOI Industrial Park @ Banting, totalling 136.03 acres, to a Bridge Data Centres entity for RM740.68 million. Hong Leong Investment Bank estimated this at about RM125 psf, with completion expected in 2Q or 3Q 2027 (Bernama). Reports differ slightly on the land area and buyer entity name; I use IOI's own figure of 136.03 acres.
- Kapar, Klang: on 19 March 2026, Maybulk, Eonmetall and Leader Steel announced conditional SPAs to sell three adjoining freehold parcels to WG Malaysia VIII Sdn Bhd for a combined RM687.89 million (RM278.05m, RM273.28m and RM136.56m). The land totals about 157 acres. Shareholders approved the disposals on 20 July 2026; completion, targeted for 2H2026, remained subject to conditions. EdgeProp links the buyer to DayOne; the filings describe it only as an IT infrastructure company.
One detail matters for everyone else. The Kapar prices were broadly in line with Savills valuations that assessed the land on its highest and best use for IT infrastructure, not its previous industrial use. In other words, where a parcel is suitable for a data centre, data centre demand can set the reference value.
Why most SME buyers are in a different lane
Both deals involve well over 100 acres, and data centres need very large power connections: a PLANMalaysia planning presentation refers to intake substations of up to 132kV or 275kV for large data centres.

A 1½-storey terrace factory or a semi-detached factory in an established park is a different product, bought by a different buyer. CBRE | WTW notes that terraced factories remained the dominant asset class in 1Q2026 because they are affordable and accessible for SMEs.
The indirect effects are what to watch:
- Large land is getting scarcer. CBRE | WTW says about 59% of the Klang Valley's roughly 54,300 ha of industrial-zoned land is developed. Mature core areas are constrained, and demand is spilling into Kundang, Banting and Bangi-Kajang-Semenyih.
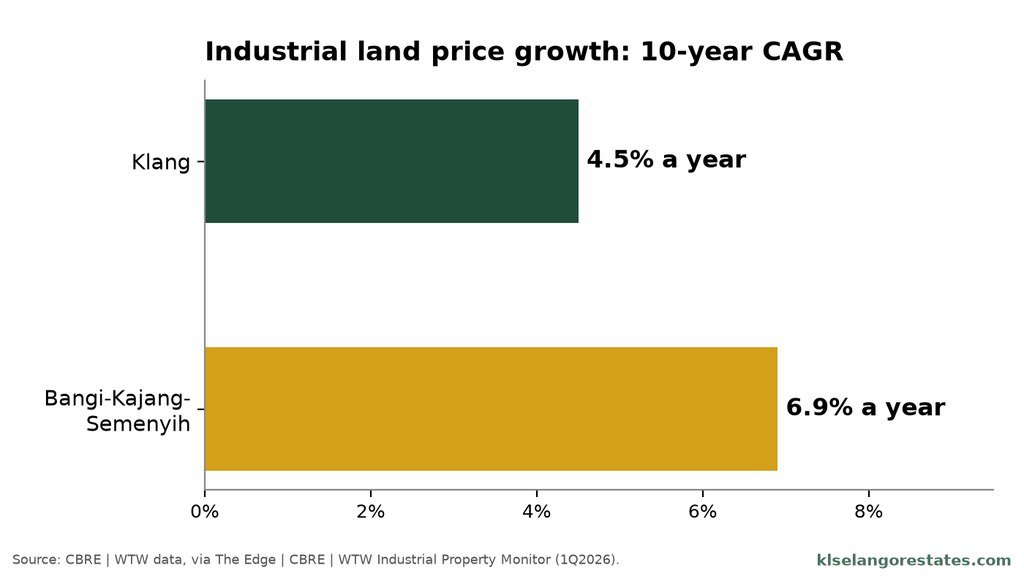
- Land prices have risen. CBRE | WTW puts 10-year industrial land price growth at 4.5% a year (CAGR) in Klang and 6.9% a year in Bangi-Kajang-Semenyih.
- Power and water are under scrutiny, and grid capacity affects everyone in an industrial area.
Policy is tightening on data centres
- MIDA says data centre and cloud projects made up RM95.8 billion, close to 44% of Malaysia's approved investments in 1H2026. Selangor led all states with RM70.0 billion across 835 projects. MIDA adds that the Data Centre Task Force clears only projects with secured power and water and demonstrable green compliance.
- On 13 October 2026, the Deputy Energy Transition and Water Transformation Minister said he had proposed that data centre operators generate their own electricity. The government is also considering requiring data centres near water sources to develop their own supply. Operating data centres had contracted about 6 GW of maximum load but used about 1.37 GW as at August 2026 (The Edge). Some press reports describe an "off-grid" condition in new award letters, but I found no published rule, so treat it as a proposal.
- Selangor introduced a separate data centre water tariff of RM5.31 per cubic metre from 1 September 2025 (Air Selangor).
- Under the Energy Commission's latest CRESS (corporate green power) changes, renewable developers pay a system access charge of 14 sen/kWh, fixed for 10 years for projects operating by 31 December 2028, and green consumers pay a further 4 sen/kWh for the current regulatory period.
For an SME, the practical point is simple: check power availability for your own site early, because grid capacity is now a national policy topic.
Terrace, semi-D or detached?
Terrace factory
- The lowest entry point, and the dominant asset class in 1Q2026 according to CBRE | WTW.
- Shared walls, limited yard space and, usually, limited container turning room.
- Suits light assembly, workshops, storage and trading businesses.
Semi-detached factory
- More land, a side yard and typically better loading access.
- CBRE | WTW reports steady demand from established SMEs and logistics-related owner-occupiers, and says average semi-D transaction prices in Petaling Jaya stayed above RM5 million in 1Q2026.
Detached factory
- Full site control, room to extend (subject to approvals) and the best truck circulation.
- A bigger ticket and fewer buyers when you sell.
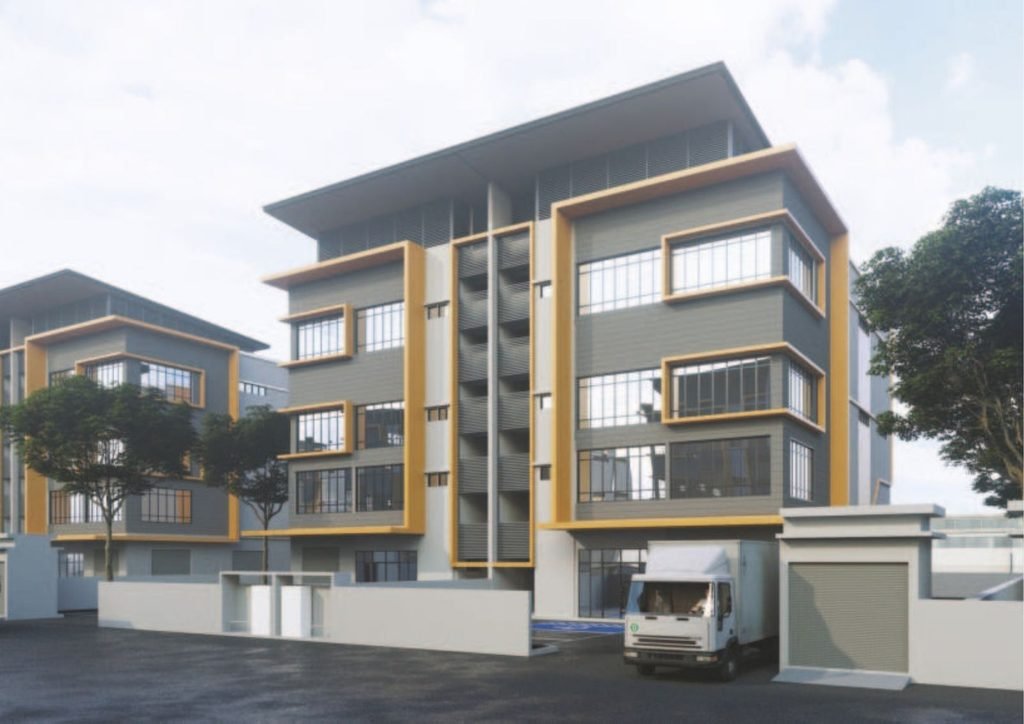
There are also multi-storey ramp-up or drive-up hubs, which suit last-mile logistics and showroom-warehouse users. Check the strata title and how the management corporation will work.
The corridors at a glance
Klang (including Bandar Bukit Raja and Kapar)
- A port-centric logistics hub, supported by Port Klang and the West Coast Expressway.
- Land price CAGR of 4.5% over 10 years (CBRE | WTW).
- The Kapar data centre land deal is here. CBRE | WTW also lists a new distribution centre of about 242,000 sq ft in Bandar Bukit Raja.
- Terrace factory prices have shown "signs of price stabilisation" recently, according to CBRE | WTW.
Kota Damansara / Petaling Jaya
- A mature, land-constrained core.
- CBRE | WTW lists a deal in Taman Sains Selangor 1 involving detached factories and an office. Sources give the price as RM65.0 million (CBRE | WTW) or RM66 million (The Edge).
- Petaling Jaya leads on semi-D values.
Kajang / Semenyih (Bangi-Kajang-Semenyih)
- The strongest 10-year land price growth of the corridors cited, at 6.9% a year, helped by the MRT Kajang Line, LEKAS and SILK.
- CBRE | WTW notes a 66-acre Semenyih industrial land purchase for RM57.0 million in 1Q2026.
- Terrace prices have recently shown signs of stabilisation.
Puchong
- Long-term upward price trends for terrace and semi-D factories, according to CBRE | WTW.
- The Edge reports a February 2026 purchase of industrial land with a factory lot in Taman Perindustrian Putra for RM23 million.
Sepang and south Selangor
- Near KLIA, with an aircraft engine test cell facility contracted at KLIA Aeropolis (CBRE | WTW). The Banting data centre sale is nearby.
- I found no published corridor-level price data for Sepang industrial property, so I won't quote any.
Due-diligence checklist
Check each of these before you sign, with your lawyer and, where needed, an engineer.
- Tenure. Freehold or leasehold? For leasehold, confirm how many years remain. Ask your banker whether the remaining lease affects financing, and ask your lawyer about renewal terms.
- Land category and express conditions. The title should show industrial use. Express conditions or restrictions in interest may limit the type of industry, require state consent to transfer or charge, or restrict leasing.
- Planning and permitted use. Confirm that your activity is allowed by the local authority, and whether it needs any licence for your process (for example, if it involves scheduled waste or emissions).
- Power capacity. Find out the existing supply (in amps and kVA, and whether it is three-phase) and whether your machines need more. Upgrades can involve TNB approval, cost and time.
- Floor loading. Usually stated in kN/m². It must suit your racking, forklifts and machinery.
- Ceiling or eave height. This decides racking height and whether cranes fit.
- Road and container access. Check internal road widths, turning space for 40-ft containers and the number of loading bays.
- CCC and Bomba. Make sure a Certificate of Completion and Compliance has been issued. Check the fire safety requirements for your use, as storage of certain goods may need additional systems.
- ESG readiness. CBRE | WTW says demand remains focused on modern, high-specification facilities. Check roof suitability for solar and energy efficiency.
- The SPA. The Housing Development Act protects buyers of "housing accommodation". Factories fall outside it, so there is no statutory SPA, and the completion dates and late-delivery compensation are whatever your SPA says. Have your own lawyer review it.
Stamp duty, RPGT and financing
Stamp duty for Malaysian buyers on the instrument of transfer follows the standard LHDN scale, whether the property is residential or industrial:
- 1% on the first RM100,000;
- 2% on RM100,001 to RM500,000;
- 3% on RM500,001 to RM1,000,000;
- 4% on any amount above RM1,000,000.
It is charged on the price or the market value, whichever is higher.
Illustration: for a RM3 million factory, duty would be RM1,000 + RM8,000 + RM15,000 + (4% × RM2,000,000 = RM80,000), which comes to RM104,000.
The loan agreement attracts 0.5% of the loan amount.
The flat 4% rate you may have heard of applies to foreign companies and non-citizen, non-permanent-resident buyers of non-residential property. For residential property, that rate rose to 8% from 1 January 2026. It is not the rate for Malaysian individuals or Malaysian-incorporated companies.
RPGT (LHDN, disposals from 2022):
- Malaysian individuals pay 30% within three years, 20% in year four, 15% in year five and nothing from year six.
- Malaysian companies pay the same rates up to year five, and 10% from year six.
If you might buy through a company, discuss it with your tax adviser first.
Financing: factories are usually financed with a commercial or business property loan, with margin, tenure and pricing depending on the bank, your financials and the property. I found no authoritative published benchmark for industrial loan margins, so I won't quote one. Get indicative offers from more than one bank, and ask how a leasehold's remaining term affects lending.
So what should an SME buyer do?
- Buy for your operation first. Power, loading, height and access matter more than headlines.
- Don't assume data centre prices apply to you. Terrace and semi-D factories trade on their own comparables.
- Watch supply. New warehouse supply in 2026 may favour tenants and buyers of logistics space.
- Check utilities early. Power and water rules are still moving.
I work with business owners looking at industrial parks across Selangor, including those listed on my industrial property page.
Sources
- The Edge Malaysia | CBRE | WTW Industrial Property Monitor (1Q2026): https://theedgemalaysia.com/node/807185
- CBRE | WTW, Klang Valley Snapshot 1Q 2026: https://cbre-wtw.com.my/wp-content/uploads/2026/05/Klang-Valley-Snapshot-1Q-2026-1.pdf
- The Edge Malaysia, "Malaysia flags growing property overhang amid slowing transactions in 1H2026" (NAPIC 1H2026 figures): https://theedgemalaysia.com/node/817533
- IOI Properties, "IOI Properties sells Banting industrial land to Bridge Data Centres for RM741m": https://www.ioiproperties.com.my/news/ioi-properties-sells-banting-industrial-land-bridge-data-centres-rm741m
- Bernama, "Land Sale Boosts IOI Properties Share Price In Mid-morning Trade" (HLIB RM125 psf estimate): https://www.bernama.com/tv/news.php?id=2520317
- Maybulk Bhd, Bursa announcement 19 Mar 2026: https://www.maybulk.com.my/investor/doc/19032026B.pdf
- The Edge Malaysia, "Maybulk, Leader Steel to pay special payouts after joint RM687.89 mil land sale in Klang with Eonmetall": https://theedgemalaysia.com/node/796927
- The Star, "Maybulk, Eonmetall, Leader Steel dispose of land" (20 Mar 2026): https://www.thestar.com.my/business/business-news/2026/03/20/maybulk-eonmetall-leader-steel-dispose-of-land
- EdgeProp, Daily Digest 24 Jul 2026 (shareholder approvals): https://www.edgeprop.my/daily-digest/2026-07-24
- EdgeProp, "AI land rush: DayOne's 157-acre Kapar play" (6 Jul 2026): https://www.edgeprop.my/content/1916643/ai-land-rush-dayones-157-acre-kapar-play-signals-data-centre-shift-towards-klang-valley
- MIDA, 1H 2026 investment performance media release: https://mida.gov.my/wp-content/uploads/2026/08/FINAL_1H2026_Investment-Performance_Media-Release_MIDA.pdf
- The Edge Malaysia, "Deputy minister proposes data centre operators generate their own power" (13 Oct 2026): https://theedgemalaysia.com/node/821622
- Air Selangor / Selangor state government, water tariff review (Aug 2025): https://content.airselangor.com/cmi-prod-blobstorageanon-001-sea/media/crolw0ze/mb-water-tariff-review-202508.pdf
- Energy Commission (Suruhanjaya Tenaga), CRESS briefing, Oct 2026: https://www.st.gov.my/sites/default/files/2026-10/CRESS-Acceleration-Package-Briefing.pdf
- PLANMalaysia, data centre planning guideline (presentation): https://stag.planmalaysia.gov.my/planmalaysia/modules_resources/database_stores/17/46_54.pdf
- LHDN, Garis Panduan Pengenaan Duti Setem (transfer scale and foreign rates): https://www.hasil.gov.my/wp-content/uploads/garis-panduan-pengenaan-duti-setem-jadual-pertama-as-1949.pdf
- LHDN, RPGT rates: https://www.hasil.gov.my/en/ckht/kadar-cukai-keuntungan-harta-tanah/
- The Edge Malaysia / TheEdgeProperty (2017), "Protect your rights when buying commercial properties" (HDA scope): https://theedgemalaysia.com/article/protect-your-rights-when-buying-commercial-properties
About the author
Jessica Leong is a Registered Estate Agent (E 3208) with PropNex Realty Sdn Bhd (E (1) 1800/1), KL branch. She covers new launch condos in Kuala Lumpur and Petaling Jaya, industrial property in Selangor, bank auction (lelong) properties, and PJ/Selangor offices, shophouses and en-bloc deals.
PropNex Realty Sdn Bhd, A-G-03, Marc Residence, No. 3, Jalan Pinang, 50400 Kuala Lumpur
Office: 03-2161 8608 · WhatsApp: 010-464 6088
Website: klselangorestates.com
This article is general information based on public sources as at 19 October 2026. It is not financial, tax, legal or engineering advice. Figures come from the sources listed and may be revised. Please consult your own lawyer, banker, tax adviser or engineer for your circumstances.