Klang Valley Shophouse Prices Rose 1.5% in 2025: What NAPIC's New Shop Price Index Means for Owners and Investors in KL, PJ and Selangor
NAPIC's first Klang Valley Shop Price Index shows steady but slower growth, with KL recovering and Petaling leading Selangor. Here are the prices, volumes and unsold stock, plus a due diligence checklist before you buy a shophouse.
Originally published on Medium: read it on Medium
For years, anyone pricing a shophouse in KL or Selangor had to piece together a few recent transactions and an agent's opinion. NAPIC, the government's National Property Information Centre, now publishes something better: the Klang Valley Shop Price Index (KV SPI).
Based on preliminary data, the index rose 1.5% in 2025, slower than 2.0% in 2024 and well below the post-pandemic peak of 5.5% in 2021. Kuala Lumpur recovered (+3.4%) after a dip in 2024, while Selangor grew more slowly (+2.2%, down from +5.4%).
This article explains what the index measures, what NAPIC's latest figures say about prices, transactions and unsold shops, and what to check before you buy, whether you plan to run your own business from the unit or rent it out.
Not advice. This is general information from NAPIC and other official sources as at 24 October 2026. The 2025 index figures are preliminary and may be revised. Please speak to your lawyer, banker and tax adviser about your own purchase.
What the new index measures
The KV SPI is NAPIC's fifth index. A few details matter when you read it:
- It covers only non-strata, one- to four-storey terraced shops in Kuala Lumpur and Selangor. Strata shop units and Putrajaya are excluded. NAPIC says stratified shops may be added in future.
- It uses 2018 as the base year (100 points) and a hedonic method, which adjusts for differences between the shops that change hands, so the index tracks price change rather than a shift in the mix of shops sold.
- It measures prices, not rents or yields. It tells you how values have moved, not what a shophouse earns.
Prices: where the index stands
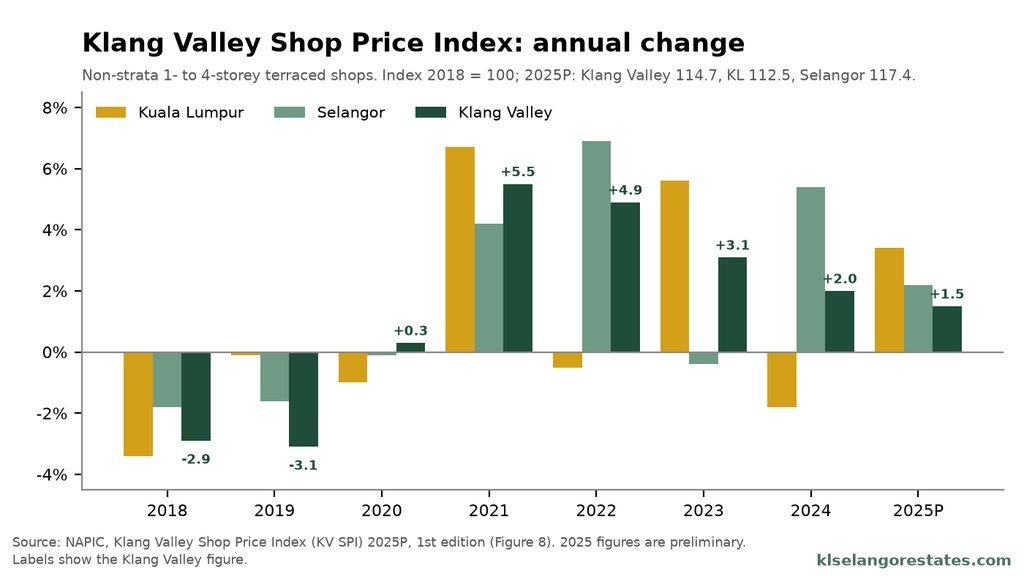
NAPIC's 2025 preliminary readings:
| Area | Index (2018 = 100) | Average price per unit | Average price per sq m | Change in 2025 |
|---|---|---|---|---|
| Klang Valley | 114.7 | RM1,507,476 | RM4,052 | +1.5% |
| Kuala Lumpur | 112.5 | RM2,465,013 | RM5,571 | +3.4% |
| Selangor | 117.4 | RM1,351,379 | RM3,798 | +2.2% |
Two points stand out. First, Selangor has gained more since 2018 than KL, but KL is still the more expensive market per unit and per square metre. Second, the index fell in 2018 and 2019, before the pandemic, and has only been positive overall since 2020. Shophouses have not been a one-way bet.
One quirk: NAPIC's overall Klang Valley figure for 2025 (+1.5%) is lower than both the KL (+3.4%) and Selangor (+2.2%) figures. The report does not explain why. It is likely to be a weighting effect, and the figures are preliminary, so I quote them as published.
By area: PJ's district leads Selangor
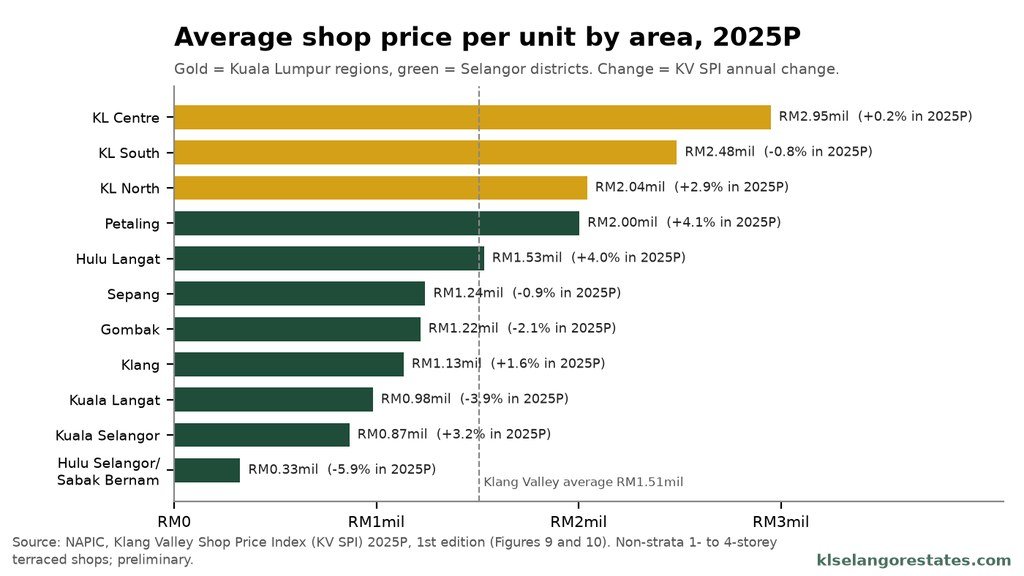
Within KL:
- KL Centre: average RM2,949,189 per unit, +0.2% in 2025. It also has the highest index reading in KL (117.0 points), so it has gained the most since 2018.
- KL South: RM2,484,417 per unit, −0.8%.
- KL North: RM2,041,416 per unit, +2.9%.
Within Selangor:
- Petaling district (which includes Petaling Jaya): average RM2,003,286 per unit, +4.1%, and the highest index in the state at 117.6 points.
- Hulu Langat: RM1,531,913, +4.0%.
- Klang: RM1,134,157, +1.6%, back in positive territory after a fall in 2024.
- Gombak (−2.1%), Sepang (−0.9%) and Kuala Langat (−3.9%) fell. Hulu Selangor/Sabak Bernam fell the most, by 5.9%, and is the most affordable at RM326,657 per unit.
The spread is wide. A shophouse in KL Centre averages more than twice the Selangor average. Even within Selangor, the "market" ranges from about RM0.3 million to about RM2 million per unit, depending on the district.
What actual transactions show
NAPIC's H1 2026 report gives examples of recent price movements:
- KL: double-storey shops in Teh Wan Sang, Lucky Garden (Jalan Bangsar), Taynton View, Happy Garden and Salak South Garden rose between 2.2% and 13.9%, with transactions between RM1.38 million and RM5 million. A three-and-a-half-storey shop in Taman Segar (average land area 143 square metres) rose 3.5%, to between RM3.12 million and RM3.40 million.
- Selangor: double- and three-storey shops in Seksyen 17 Shah Alam, Bandar Sunway Semenyih, TTDI Jaya, Putra Heights and Bandar Pinggiran Subang changed hands at between RM2.50 million and RM4.20 million. Three-storey shops in Bandar Puteri Bangi rose 9.7% (RM1.95 million to RM2.00 million) and in Bandar Puteri, Petaling, 9.4% (RM2.80 million to RM2.92 million).
Volumes: busy, and moving upmarket
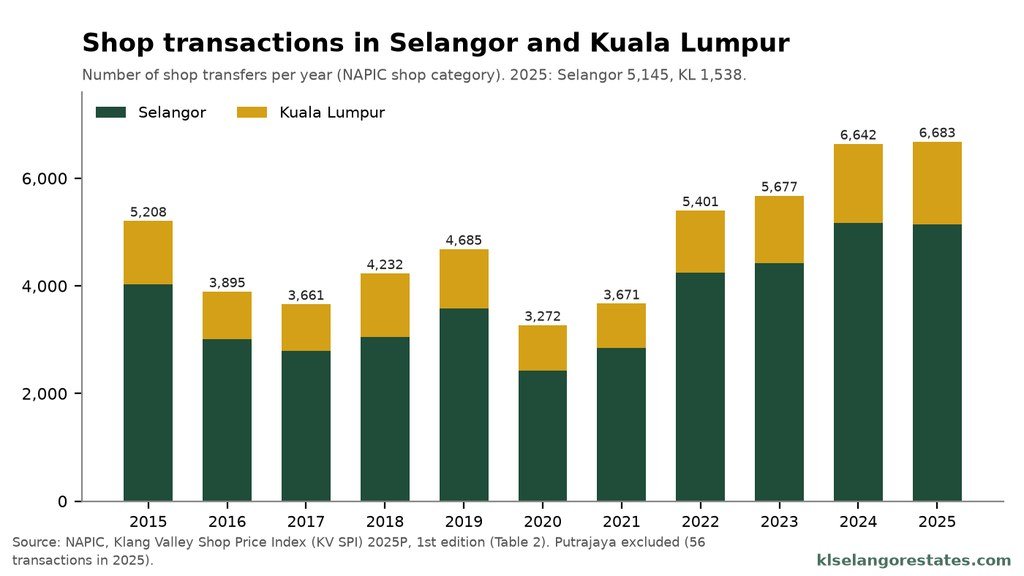
- In 2025, Malaysia recorded 23,771 shop transactions. The Klang Valley accounted for 6,739 (28.3%): 5,145 in Selangor, 1,538 in KL (the highest for KL in the 11 years NAPIC shows) and 56 in Putrajaya.
- Price points are high. In 2025, 50.8% of Klang Valley shop transactions were above RM1 million. Nationally, 60.1% were above RM500,000.
- In H1 2026, Malaysia recorded 9,060 shop transactions worth RM9.67 billion, slightly fewer deals than in H1 2025 (9,147) but higher in value (RM9.00 billion).
- Selangor recorded 1,796 shop transactions worth RM2.88 billion in H1 2026: second nationally by volume (19.8%, behind Johor) and first by value (29.8%). Within the Central Region, KL took 17.0% of shop transactions by volume and 28.9% by value.
- Two- to two-and-a-half-storey shops are the most traded type nationally, at 54.1% (4,904 transactions), followed by three- to three-and-a-half-storey shops at 27.7% (2,507).
Supply and unsold shops
The pipeline in the Klang Valley is far smaller than a decade ago. Comparing 2015 with 2025:
| State | Existing stock 2015 | Existing stock 2025 | Incoming 2015 | Incoming 2025 | Planned 2015 | Planned 2025 |
|---|---|---|---|---|---|---|
| Kuala Lumpur | 25,441 | 30,973 | 1,429 | 561 | 1,119 | 181 |
| Selangor | 86,352 | 113,246 | 14,390 | 5,418 | 7,342 | 2,287 |
Unsold shops at H1 2026:
- Selangor: 491 completed and unsold, 838 under construction and unsold, and 110 not yet constructed and unsold.
- Kuala Lumpur: 60 completed and unsold (up from 10 in H2 2025), 7 under construction and none not yet constructed.
Building activity in Selangor picked up. In H1 2026, 649 shop units were completed (H1 2025: 166), 713 were started and 372 were newly planned. KL recorded 38 starts and no completions.
Nationally, 6,124 completed shops were unsold in H1 2026, worth RM4.67 billion. The age profile is telling. 50.9% have been on the market for six to ten years, and 28.3% for more than ten. Many unsold shops are not new launches waiting for buyers but older stock that the market has passed over. NAPIC's report links weaker demand in secondary areas to e-commerce and changing consumer habits, with demand shifting towards uses such as F&B, last-mile logistics and services.
Rental context: what NAPIC reports
NAPIC does not publish a shop rental index, but its H1 2026 report gives ground-floor rents for selected areas:
- Jalan Sultan Ismail, KL: RM17,000 to RM25,000 a month, the highest in the country.
- Bangsar Baru: RM15,000 to RM19,000 a month.
- Desa Sri Hartamas: RM8,000 to RM19,000 a month.
- Petaling district, central town prime areas: RM2,500 to RM8,000 a month.
- Taman Melawati, Seksyen 7 Bandar Baru Bangi and Taman Pelangi Semenyih: rents rose more than 8%, to between RM3,100 and RM7,800 a month.
- Bandar Setia Alam and Bandar Baru Ampang: RM7,000 to RM8,500 a month.
These are ground-floor rents for selected streets, not averages. They do not tell you what the upper floors earn or what a particular unit will rent for. I have not combined them with the price data to estimate yields, because NAPIC does not publish them on a matched basis.
What it means for owner-occupiers and investors
If you will run your business from the shop:
- In 2025, the index moved between −5.9% and +4.1% across areas. That is a reminder that much of the value of owning comes from not paying rent and controlling your premises, not from quick capital gains.
- The difference between areas is larger than the change in any one year. Choosing the right street matters more than timing.
If you are buying to rent out:
- Check the unsold stock and incoming supply in the immediate area, not just the state total.
- Ask for the current tenancy, rent history and any vacancy periods, and test whether the tenant's business type (F&B, services, clinics, tuition) fits the area's demand.
- If your total taxable rental income exceeds the service tax registration threshold, service tax may apply (see below).
Due diligence checklist before you buy a shophouse
- Title type: individual or strata. The index covers individual-title (non-strata) terraced shops. Strata shop units come with a management body, maintenance charges and sinking fund contributions, and are priced differently. Under the Strata Titles Act 1985, ending a strata scheme needs a unanimous resolution, which matters if you are hoping for redevelopment one day.
- Category of land use and express conditions. Under section 52 of the National Land Code, alienated land falls into one of three categories: agriculture, building or industry. Check that the title's category and express condition allow commercial use. Changing them needs an application to the State Authority under section 124. In Selangor, these applications have been made through the e-Tanah system since 26 October 2023.
- Tenure and restrictions in interest. Check whether the land is freehold or leasehold, how many years remain on a lease, and whether a transfer or charge needs state consent. Your lawyer's land search will show this.
- Financing. Banks value commercial property on its own merits, so get the bank's valuation before you commit. NAPIC suggests owners can use the index to benchmark values for financing or refinancing. Treat it as a guide only, because the averages mix very different streets.
- Stamp duty. The transfer is charged on the price or market value, whichever is higher, at 1% on the first RM100,000, 2% up to RM500,000, 3% up to RM1 million and 4% above that. On a RM2 million shophouse, that comes to RM1,000 + RM8,000 + RM15,000 + RM40,000 = RM64,000. A loan agreement is charged at 0.5%, so an RM1.6 million loan costs RM8,000 in duty. Foreign buyers pay a flat 4% on non-residential property, which on RM2 million is RM80,000. From 1 January 2027, a transfer under an SPA moves to self-assessment on MyTax. See my guide to stamp duty self-assessment.
- RPGT when you sell. For Malaysian citizens and PRs, LHDN's rates are 30% on gains if you sell within three years, 20% in the fourth year, 15% in the fifth and 0% from the sixth. Malaysian companies pay 10% from the sixth year, and foreign owners pay 30% up to the fifth year and 10% after.
- Service tax on rent. Rental or leasing services have been subject to service tax since 1 July 2025. According to the Royal Malaysian Customs Department, the rate has been 6% from 1 January 2026, and the Ministry of Finance set the registration threshold at RM1 million of taxable services in 12 months. Most individual shophouse landlords will be below that, but check with your tax adviser.
- En-bloc potential. A row of individually titled shophouses can sometimes be assembled for redevelopment, but every owner has to agree to sell, and the titles then need to be amalgamated and the plans approved. Don't pay a premium for "en-bloc potential" unless there is real evidence of interest. I have written about structuring en-bloc acquisitions in Selangor and the stalled Urban Renewal Bill.
For examples of specific shophouse areas in PJ, see my articles on SS2 and Damansara Uptown. If you are considering an auction unit, my bank lelong guide covers the process.
What is still not confirmed
- The 2025 index figures are preliminary and may be revised in NAPIC's next edition.
- Why the overall Klang Valley figure (+1.5%) is lower than both the KL and Selangor figures. NAPIC's report does not say.
- H1 2026 index readings. NAPIC's KV SPI is annual, and the 2026 figure had not been published as at 24 October 2026.
- Yields. No official source publishes matched shop prices and rents, so I have not estimated yields.
Sources
- NAPIC, Klang Valley Shop Price Index (KV SPI) 2025P, 1st edition: https://napic.jpph.gov.my/storage/app/media/3-penerbitan/Shahrul/Bahagian%20Indeks%20Harta%20Tanah/Laporan%20Jadual%20SHPI/Q4%202025/Report%20%20KV%20SPI%201st%20Edition%202025_update.pdf
- NAPIC, Property Market Report H1 2026: https://napic.jpph.gov.my/storage/app/media/3-penerbitan/Shahrul/Bahagian%20Pasaran%20Harta%20Tanah/Laporan%20Pasaran%20Harta%20Separuh%20Tahun%20dan%20Jadual/Q2%202026/LAPORAN%20PASARAN%20HARTA%20H1%202026.pdf
- NAPIC, Property Market Status Report H1 2026: https://napic.jpph.gov.my/storage/app/media/3-penerbitan/Shahrul/Bahagian%20Inventori%20Harta%20Tanah/Laporan%20Jadual%20Status%20Harta%20Tanah/Q2%202026/Laporan%20Status%20Harta%20Tanah%20H1%202026.pdf
- Pejabat Tanah dan Galian Selangor, Permohonan Tukar Syarat Tanah, section 124(1)(a) and (c), National Land Code: https://ptg.selangor.gov.my/index.php/pages/view/229
- JKPTG, Pekeliling Ketua Pengarah Tanah dan Galian Persekutuan Bil. 1/2003 (on the land use categories in section 52 of the National Land Code): https://www.jkptg.gov.my/my/panduan/senarai-pekeliling/pekeliling-terbuka?element=541ef889-0fe4-4928-87d5-58cb597ed2e7&format=raw&item_id=1218&method=download&task=callelement
- Stamp Act 1949 (Act 378), First Schedule, Items 27 and 32: https://mylaw.my/legislation/stamp-act-1949/section-36
- LHDN, Real Property Gains Tax rates (updated 23 June 2026): https://www.hasil.gov.my/en/ckht/kadar-cukai-keuntungan-harta-tanah/
- Royal Malaysian Customs Department, MySST, Service Tax background: https://mysst.customs.gov.my/background/
- Ministry of Finance, media release on revisions to the SST (27 June 2025): https://mof.gov.my/portal/images/2025/06/27/Media-Release-Revisions-to-the-SST-take-into-account-public-and-industry-feedback.pdf
- Strata Titles Act 1985 (Act 318), section 57
About the author
Jessica Leong | Registered Estate Agent E3208
PropNex Realty Sdn Bhd (E (1) 1800/1), KLCC branch. Jessica covers new launch condos in Kuala Lumpur and Petaling Jaya, industrial property in Selangor, bank auction (lelong) properties, and PJ/Selangor offices, shophouses and en-bloc deals.
PropNex Realty Sdn Bhd, A-G-03, Marc Residence, No. 3, Jalan Pinang, 50400 Kuala Lumpur
Office: 03-2161 8608 · Call/WhatsApp: 010-464 6088
Website: klselangorestates.com
This article is general information based on public sources as at 24 October 2026. It is not legal, tax or financial advice. NAPIC's 2025 index and H1 2026 figures are preliminary and may be revised. Please consult your own lawyer, banker and tax adviser before buying.